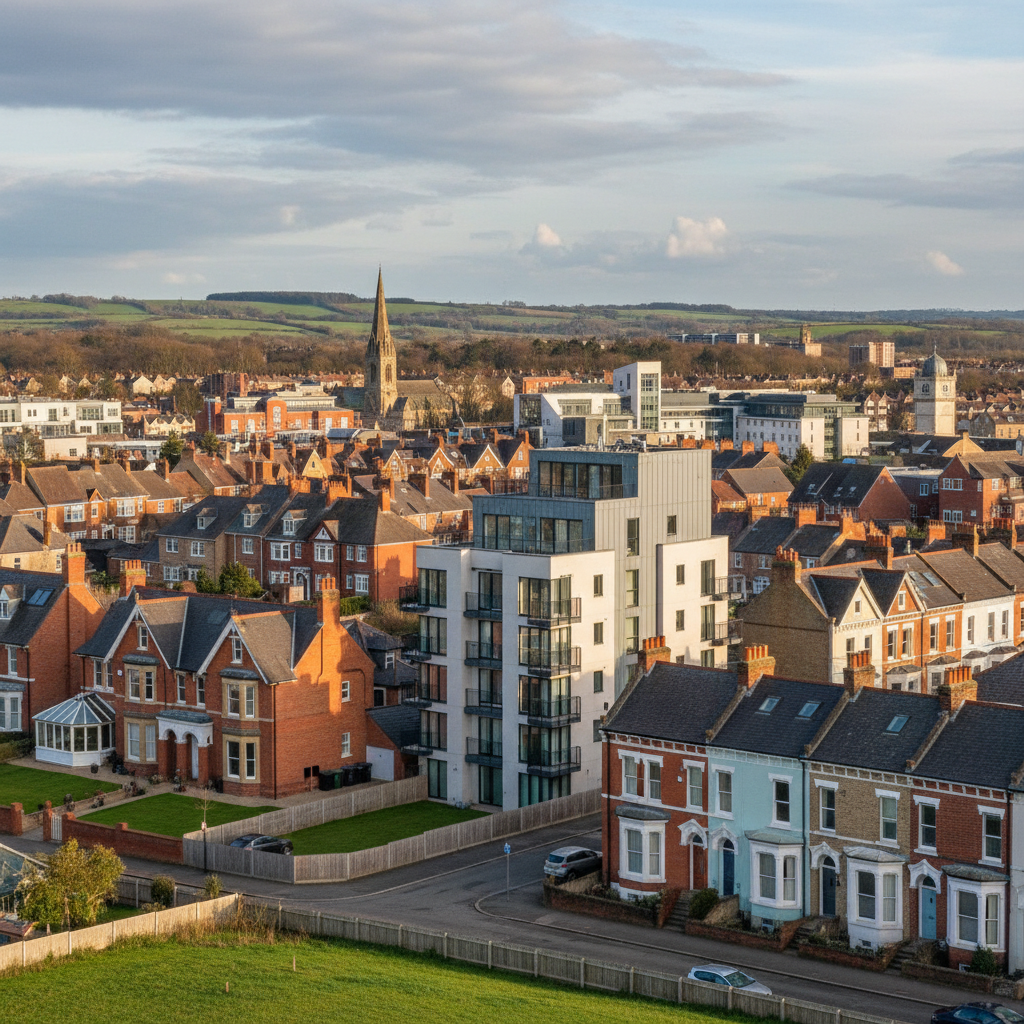
Is the Small-Space Revolution Starting in CM11 1? Why Apartment Life is Turning Heads this March
I was walking through Ramsden Heath the other day, grabbing a coffee, and I noticed something that really tickled my brain. While we often think of our patch of CM11 1 as the land of sweeping driveways and big gardens, the conversation at the school gates and the local pubs is shifting. People aren't just talking about the biggest houses anymore; they’re looking at the smarter, smaller ways to get onto the property ladder.
Did you know that despite all the talk of "boring" markets, the gap between a flat and a big detached home in CM11 1 is now wider than the Grand Canyon? If you look at the price tags today, a detached house will set you back about £912,580. But here’s the kicker: a semi-detached is sitting at £489,733. That’s a difference of over £422,000! To put that in perspective, for the price of one big detached house in Downham, you could nearly buy two semi-detached homes and still have enough left over for a very fancy sports car.
It’s not just about the price today, though—it’s about how much extra "potted gold" has appeared in people's pockets over the last few years. If you bought a semi-detached home in CM11 1 seven years ago, your home is worth £21,274 more today. If you went for a big detached place, perhaps over in Ramsden Bellhouse, you’ve seen your "house wealth" grow by a whopping £34,806.
So, why are flats becoming the talk of the town this March? It all comes down to what’s happening at the big banks in London. Right now, the Bank of England has kept the "base rate"—basically the price they charge other banks to borrow money—at 3.75%. When you pair that with prices of daily things (like bread and milk) rising at 3.2%, people are being much more careful with their pennies.
Because it’s getting a bit more expensive to borrow money for a mortgage, many people who were looking at terraced houses are now peeking at flats instead. It’s like when the price of prime steak goes up; more people start looking at the really nice gourmet burgers. In CM11 1, this means flats are no longer just for people starting out; they are becoming a clever way to stay in a beautiful area without needing a lottery win to cover the monthly bills.
If you’re lucky enough to own one of those gorgeous detached houses on Homestead Road or Glebe Road, the outlook is still very steady. Unlike other parts of the country where prices are bouncing around like a toddler on a trampoline, CM11 1 is a "balanced market." This means there’s a nice even mix of people selling and buying, so you aren't in a rush to make a move.
But for my friends looking to buy their first home? Reality can be a bit of a squeeze. With wages growing at about 3.1%, it’s a race to keep up with house prices. If you are looking for the "best bang for your buck," the growth we’ve seen in semi-detached houses (4.5% over seven years) shows that they are the real workhorses of our local market.
Looking ahead to the rest of 2026, I reckon the "middle ground" properties—the terraces and the flats—are going to be the ones to watch. As more people get used to the current borrowing costs, the demand for these manageable, stylish homes is going to bubble up. Whether you're in a cosy flat or a sprawling mansion, CM11 1 remains a special little corner of the world where your home is doing much more than just keeping you dry—it’s building your future, one brick at a time.